How to Stay Budget Motivated Recently, I started to do budgeting to save some money every month. I noticed one thing: having many expenses like current bills & rent for the house, groceries & unexpected expenses. By this only a little amount of money is left with us.
So, I make a list of monthly expenses first, generally what is really needed exactly, & by this started saving some amount.
I set a goal of 2000 dollars. I started by saving some money for a few months, & finally I built the saving habit rather than saving a large amount of money.
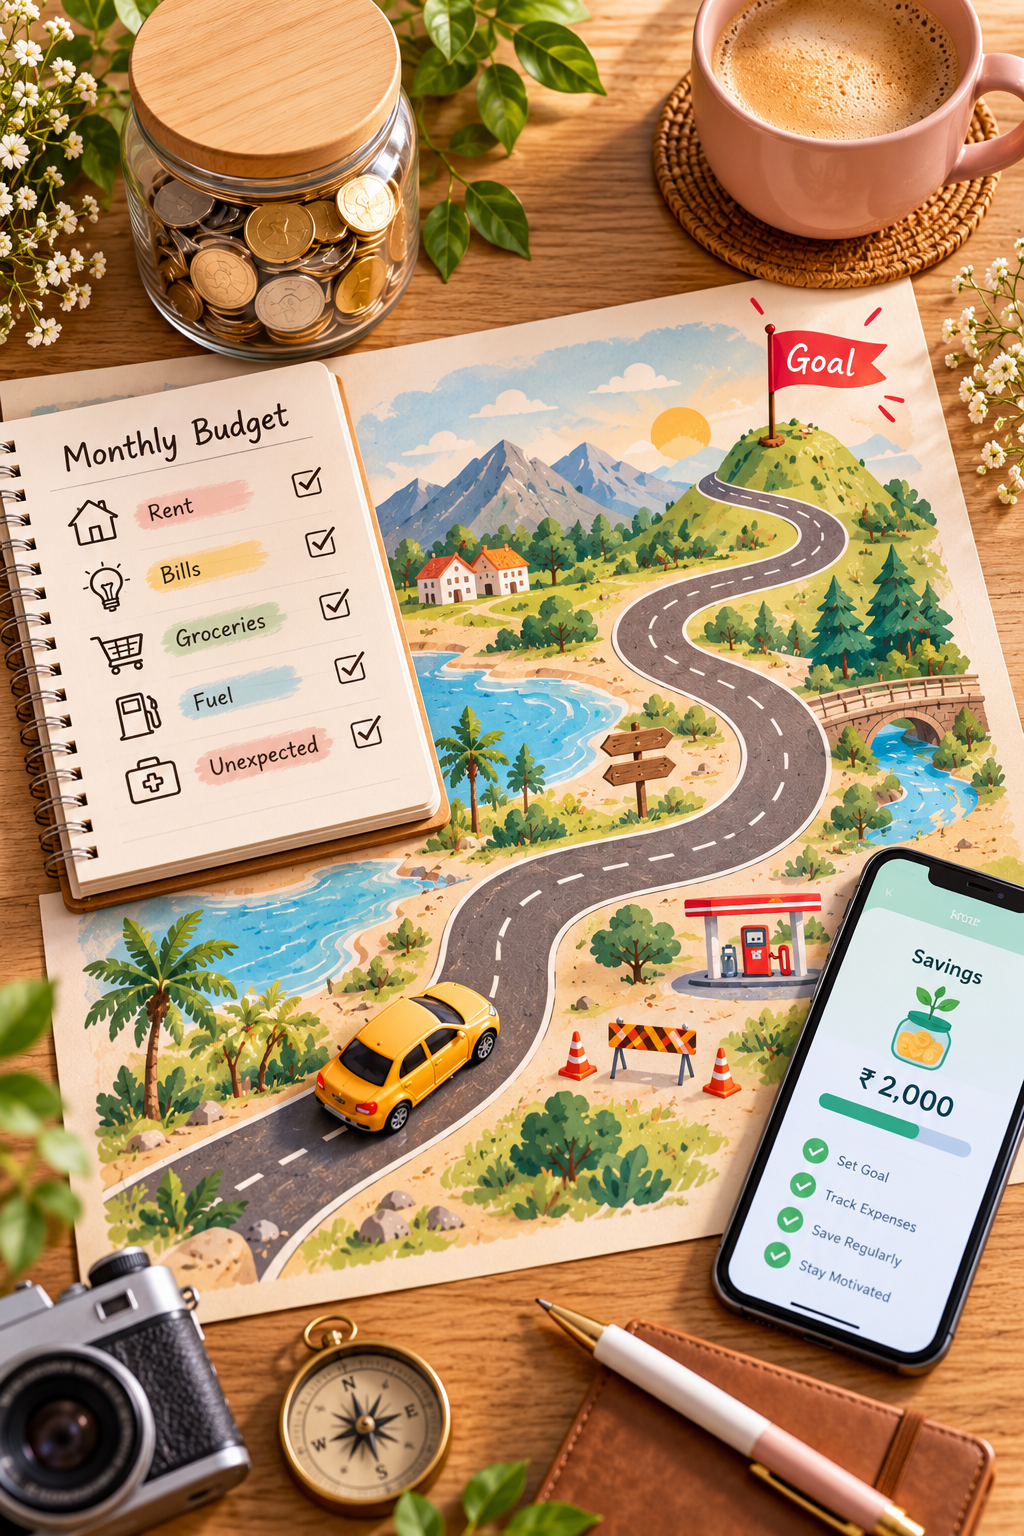
Think of a budget like a journey. If we plan a trip and we know the destination, but in the middle sometimes we have to make wrong turns & stop for petrol & traffic jams on the roads, let’s get back to the present budgeting track & keep going.
Many people leave their budget after one bad day or week & walk away like leaving a car in traffic.
So in this article, we have 10 simple budget tips for beginners to work even when we have low enthusiasm days.
What is budget motivation?
Budget motivation means that you stay connected to a spending plan: you check it, you adjust it, and you actually follow through, even after the novelty of building it wears off. It’s not one emotion. There are a number of factors involved, including the clarity of your financial objectives, the progress you can actually see, and the extent to which your day-to-day budgeting habits fit into a normal life.
1. Make a Decision on Your Budget Goal
Firstly, put a goal & start your budget by “saving money,” so start writing your goal with a number & a date. It generally starts with. (How to Motivate Yourself to Stick to Your Budget)
For example,
Here are some of the simplest tips, for example:
- Save a $5,000 emergency fund by next December.
- Keep a mode of payoff of $3,000 in credit card debt annually or in the next 12 months.
- Keep some money for paying house down payments in two years; put an amount like 2000 dollars.
So, this can stop you when you want to buy unnecessary things. If you have to sacrifice, the aim will be reached later.
2. Check Your Spending for One Month
Many of the beginners make a budget plan without knowing how much money they actually spend. For the first month, write down everything in a detailed expense without changing your spending habits.
Firstly, check your bank statements & credit card statements to know where your money goes. After one month, make a budget based on what you were actually spending.
For example:
If you spend $700 on groceries every month, reducing it to $400 suddenly may make it feel difficult.
Try to reduce it slowly. First spend $650, then $600 & later $550. Remember, habits do not change in a single day.
If you set a very low limit & cross it in the first week, you may feel bad about your spending. So, set a realistic budget.
For example, if you spent $2,650 last month and earned $3000, you have $350 to work with to save.
3. Plan for your days
Some days you’ll feel tired and won’t want to look at your budget. Know in advance what your “bare minimum” is: what’s required is two minutes to check your balance and to note any big bill that is coming up. The minimum keeps the habit alive.
4. Match your pay to your budget
If your rent due is the 3rd but you get paid on the 10th, you may feel tight. Plan your due dates with your paydays accordingly, and split the bills. a budget that fits your calendar; it is easy to follow.
5. Use Your Company’s Savings Benefits
Some companies give extra money when employees save for retirement.
For example, a company may add money when you contribute to its retirement plan. in the US this is often called an employer match on a 401(k). Check how much your company will add. Ask your HR department about their rules.
If you have a lot of credit card debt, ask a financial advisor for help.
6. Don’t cut out the fun.
When I go on a trip, I need to break and have a coffee. If you go on a road trip without stopping anywhere and without even drinking tea, you will be tired. So is the budget? Many budgets fail because they seem like a punishment.
Keep a small amount, such as $50-$80 per month, as you like. It can be like a book, a movie, or a meal.
When you spend money accordingly that you have already planned for, you will not feel like you are spending too much.
This is because you have already included it in your budget. Decide how much money fits your income and goals.
7. Setting Small Goals
When a card balance is zero, or a quarter of the total debt is gone, have a no-cost mini-celebration: cooking your favorite meal at home, a walk in the park, or an evening with friends.
That celebration should not pull back your goal, that’s all. Break big savings into small milestones.
8. Wait for a while before buying.
If your small purchases are your weakness, wait 24-48 hours and buy. If you have a problem with large purchases, like $300 wait a week. This is not the rule of “I buy nothing,” but the rule of “I think and buy.”
9. Budgeting review
If life changes, the budget must also change. Changing the numbers doesn’t fail when it comes to car repairs, medical bills, family changes, etc.; it’s all part of the plan.
Putting aside the amount of small “unexpected expenses,” such as $50-200 per month before things like this, can reduce stress.
10. Keep a companion on the journey.
Tell a single person you’re confident about your goal: spouse, friend, sibling, or anyone. Say, “Ask me once a month how my savings are.” We are more honest with ourselves when we know that someone will ask.
Group chat is not required; there is no need to advertise on the Internet. One person is enough.
A Worked Example: One Month on a $3,200 Income
Numbers make a budget feel real. Here is one sample month for someone who takes home $3,200. These are example figures, so copy them in your own.
| Category | Planned amount |
| Rent | $1,300 |
| Groceries | $500 |
| Transportation | $300 |
| Utilities and phone | $250 |
| Minimum debt payments | $200 |
| Savings goal | $300 |
| Fun money | $100 |
| Cushion for surprises | $100 |
| Extra toward one goal | $150 |
| Total | $3,200 |
Now picture a $120 surprise car repair in week two. The $100 cushion covers most of it, you trim $20 from fun money, and the plan survives. That is what a budget with some room in it does.
This advice is not fit for
If your bills and needs are more than your income, it is not fit for you; contact lenders or landlords about payment options. In the US you can do Dail 211 local assistance programs
The last word
Being consistent is more important than being perfect. It’s much more powerful to follow a plain budget for three years than to follow a perfect budget for three months.
What to do this week:
1. Write your goal in one word.
2. Take 15 minutes to look at your spending this Sunday.
3. Check to see if your savings are going to be automatic.
This article is only for general information. This is not personal financial or tax advice.